Bitcoin rose 12% in eight days and perp funding barely moved
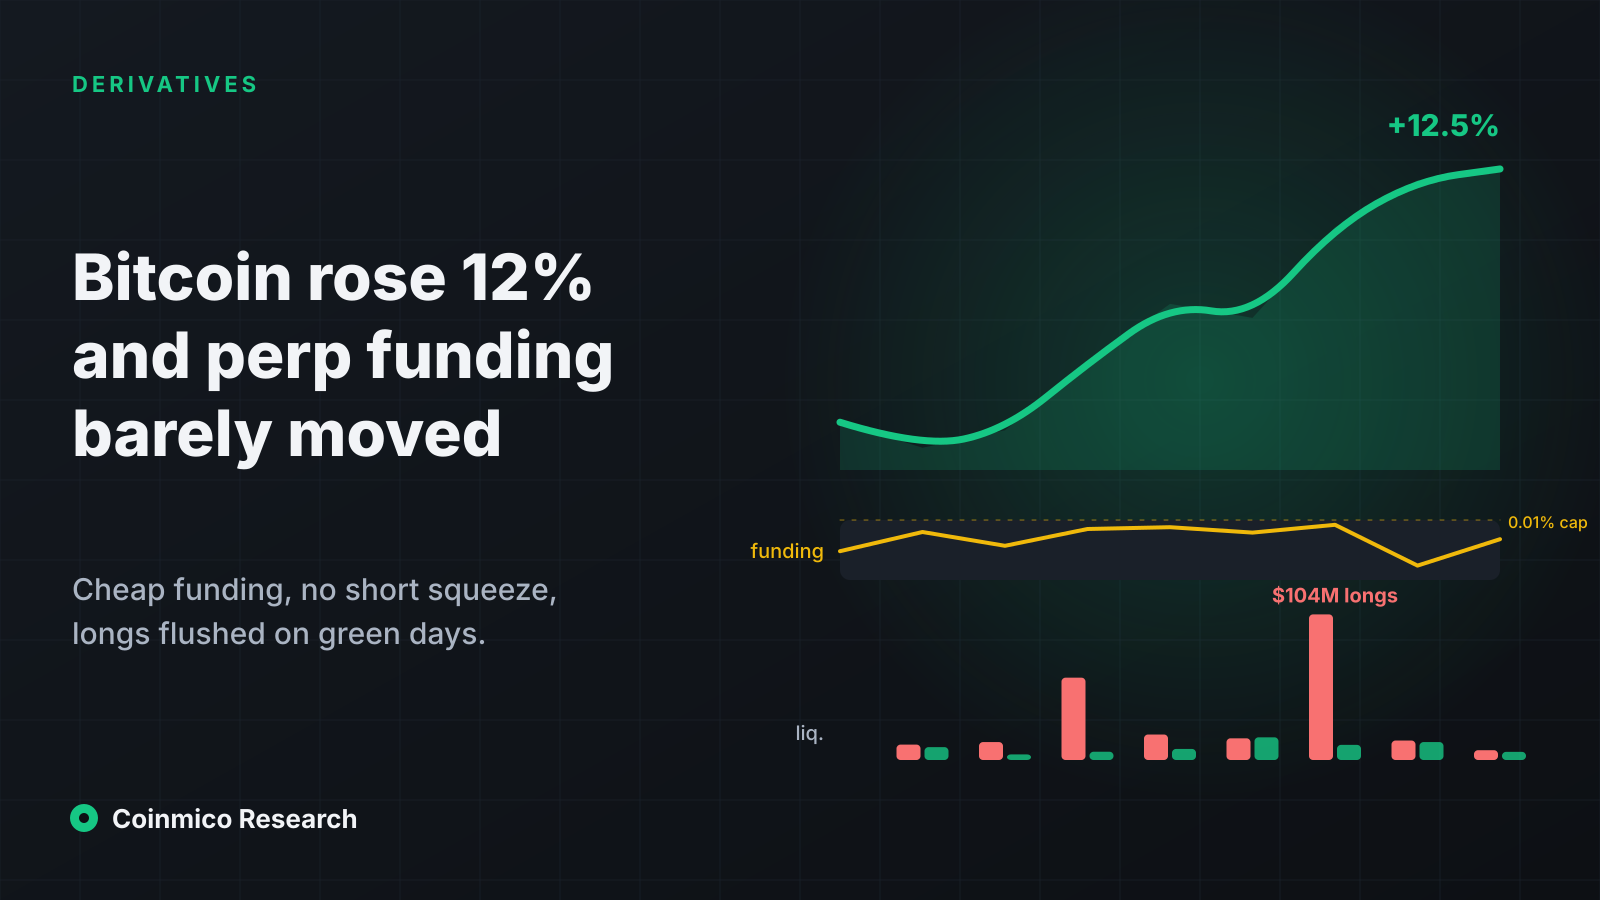
A leveraged rally shows up as funding rates pinned at the cap and shorts being squeezed. This one shows neither. Funding on the three largest perp venues averaged 0.006% per eight hours, short liquidations never exceeded $16M a day, and the biggest liquidation days were longs being flushed on up-days.
Key findings
- Between 15 and 23 September bitcoin's index price went from $76,809 to $86,403 (+12.5%). Average eight-hour funding on Binance, Bybit and OKX ranged 0.002%–0.009%, an annualised 3–10%, touching the 0.01% default cap only on 19–20 September.
- Open interest in bitcoin perpetuals stands at $26.6B across the seven venues we poll — Binance $9.1B, Bybit $5.2B, Hyperliquid $3.9B, Bitget $3.0B, Gate $2.7B, OKX $2.6B. Ether perps hold $17.3B.
- Long liquidations dominated. $58.8M of longs were liquidated on 18 September and $104M on 21 September — both days bitcoin closed higher. Short liquidations peaked at $16.2M on 20 September.
- This is the signature of a spot-led move with intraday shakeouts of leverage, not a short squeeze and not a funding-driven melt-up.
There are two ways a 12% week happens in bitcoin. In a leverage-led rally, perp traders pile into longs, funding rates pin to their cap, open interest balloons, and every dip is bought with borrowed money until a cascade of long liquidations ends it. In a spot-led rally, someone is buying actual coins; perps follow the spot price, funding stays modest, and the liquidations that do happen are stale longs getting shaken out on wicks rather than shorts being run over.
The 15–23 September move looks like the second kind. Here is the evidence, all measured from our own feeds.
 BitcoinBTCPrice, last 30 days+6.60%
Funding stayed cheap
Funding is what perp longs pay shorts (or the reverse) to keep the contract price near spot. When everyone wants to be long, it goes up. Binance, Bybit and OKX settle every eight hours with a default cap of 0.01%.
| Date | BTC index (avg) | Avg 8h funding, big-3 | Annualised |
|---|---|---|---|
| 15 Sep | $76,809 | 0.0048% | 5.3% |
| 16 Sep | $75,843 | 0.0080% | 8.8% |
| 17 Sep | $76,505 | 0.0057% | 6.2% |
| 18 Sep | $79,023 | 0.0085% | 9.3% |
| 19 Sep | $81,292 | 0.0088% | 9.6% |
| 20 Sep | $80,762 | 0.0079% | 8.6% |
| 21 Sep | $84,200 | 0.0092% | 10.1% |
| 22 Sep | $85,975 | **0.0024%** | 2.6% |
| 23 Sep | $86,403 | 0.0068% | 7.4% |
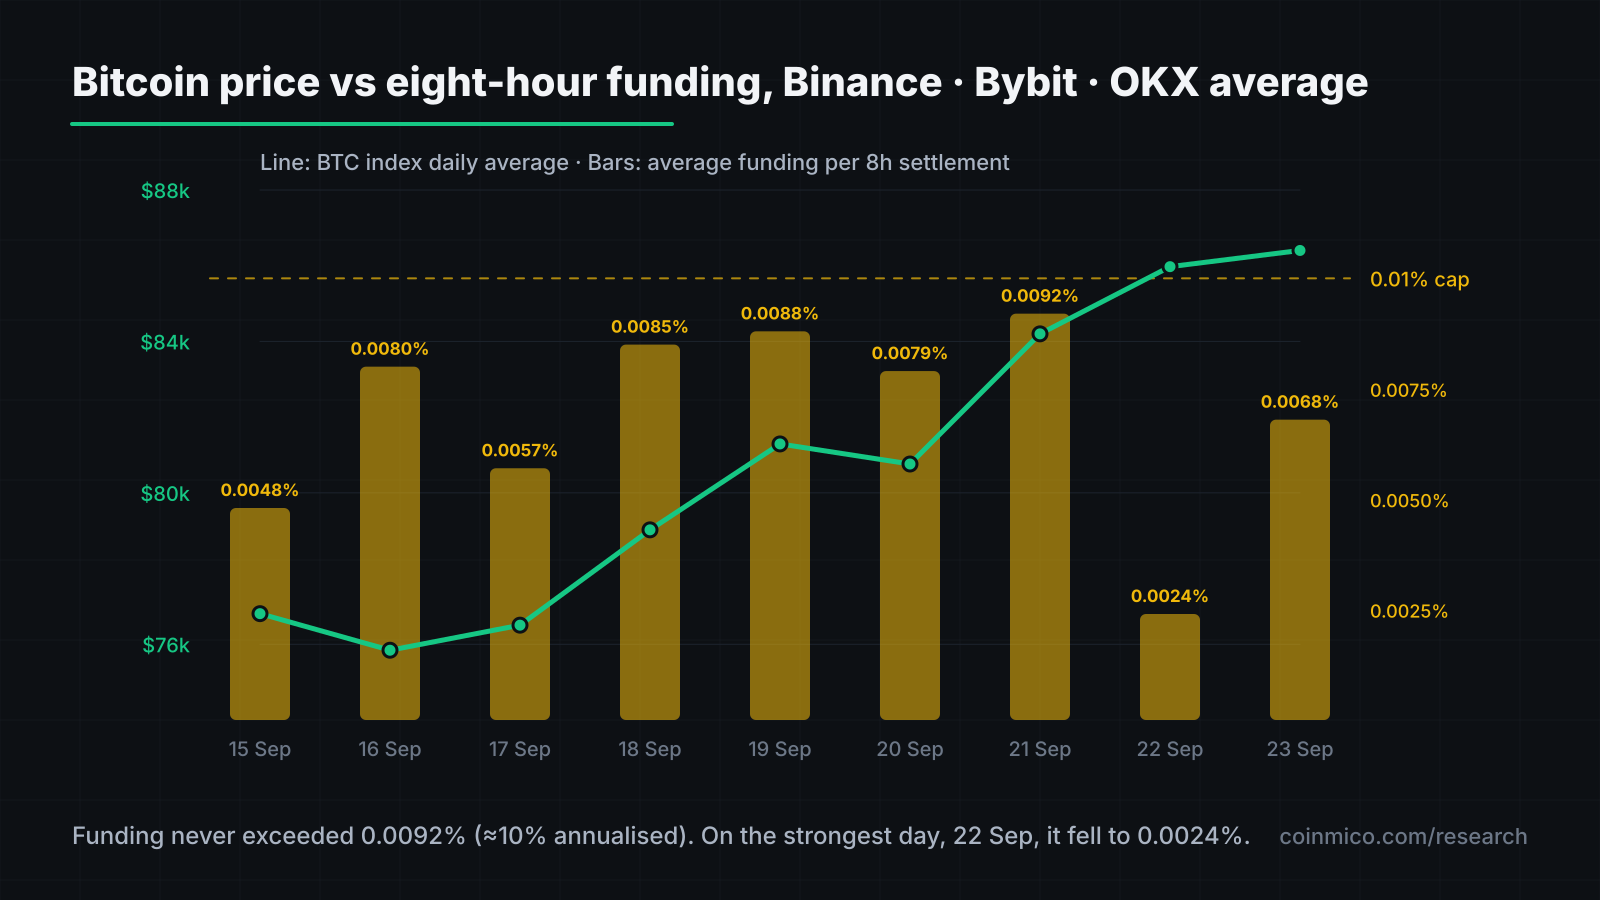
Funding did rise with the price, and Binance's rate sat at the 0.01% cap for several consecutive settlements on 19–21 September. But the cap is the _normal_ state of a mildly bullish market: 0.01% per eight hours is about 11% a year, roughly what a spot-margin lender charges. A genuine leverage frenzy pushes rates past the default cap — venues allow several times more on most contracts — and takes the annualised rate into the 30–100% range. That never happened.
More telling: on 22 September, the strongest day of the rally (+2.1% on the daily average, a new high at $86k), funding collapsed to 0.0024%. Perp longs were not chasing. Hyperliquid, which settles hourly, showed 0.00125% per hour — equivalent to 0.01% per eight hours — throughout.
Open interest: large but not stretched
At the time of writing, bitcoin perpetual open interest across the seven venues we poll is $26.6B:
| Venue | BTC perp OI | Share |
|---|---|---|
| Binance | $9.13B | 34% |
| Bybit | $5.16B | 19% |
| Hyperliquid | $3.94B | 15% |
| Bitget | $3.01B | 11% |
| Gate | $2.74B | 10% |
| OKX | $2.64B | 10% |
Ether perps hold $17.3B, Solana $3.7B, HYPE $3.2B, Zcash $2.5B, XRP $1.9B. Zcash's position at fifth — ahead of XRP and Dogecoin — is unusual and reflects the privacy-coin rotation of the past two weeks.
A 12% price rise mechanically lifts dollar OI by about 12% even if no one opens a position, since contracts are quoted in coins. Beyond that mechanical effect we do not see the doubling of OI that marked the leverage-driven runs of 2021 and early 2024. Our OI history is short (we began polling in late August), so we are cautious about trend claims; the derivatives panel on the bitcoin page shows the series as it fills in.
Liquidations: longs got flushed on green days
This is the clearest tell. Liquidations are forced closes when a leveraged position's margin runs out. In a short squeeze you see short liquidations spike on up-days. Here is what actually happened:
| Date | BTC daily change | Long liquidations | Short liquidations |
|---|---|---|---|
| 16 Sep | −1.3% | $11.0M | $9.2M |
| 17 Sep | +0.9% | $12.8M | $4.0M |
| 18 Sep | +3.3% | **$58.8M** | $5.9M |
| 19 Sep | +2.9% | $18.2M | $7.9M |
| 20 Sep | −0.7% | $15.5M | **$16.2M** |
| 21 Sep | +4.3% | **$104.0M** | $10.8M |
| 22 Sep | +2.1% | $13.9M | $12.8M |
| 23 Sep (partial) | +0.5% | $7.0M | $5.8M |
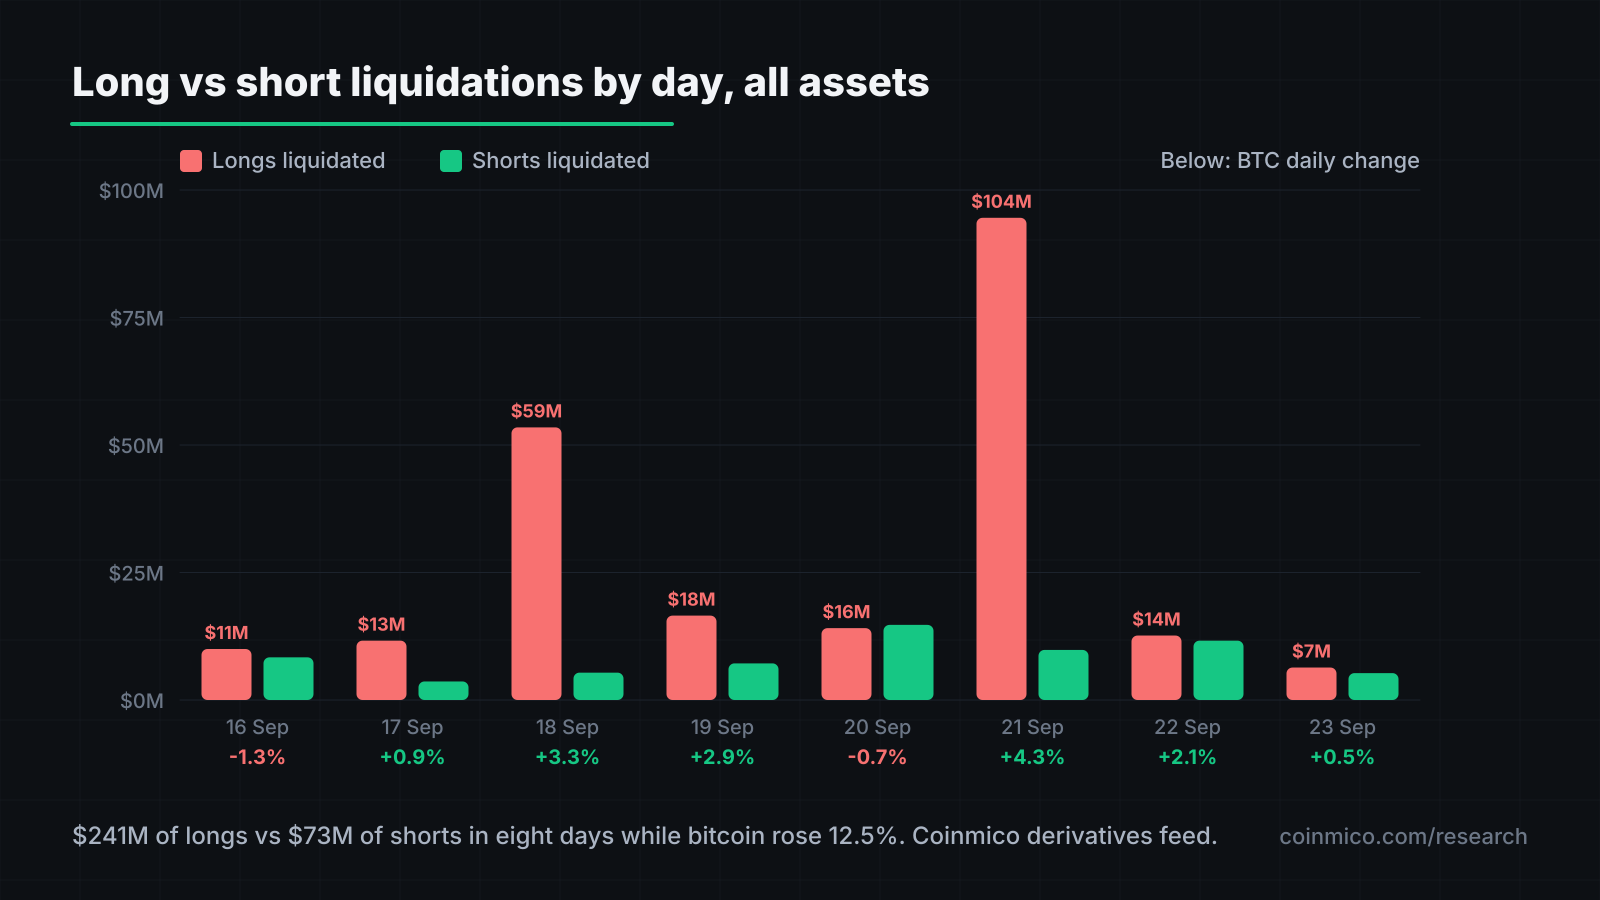
Over the eight days, $241M of longs were liquidated against $73M of shorts — a ratio of 3.3 to 1, on a week when the price went _up_. The two largest liquidation days, 18 and 21 September, were both strong up-days for the daily close. That pattern only makes sense if the price wicked sharply lower intraday before recovering: leveraged longs entered on the breakout, got stopped out on the dip, and spot buyers then carried the price higher without them.
Short liquidations never exceeded $16.2M in a day, and that peak came on 20 September, a _down_ day. The shorts that would fuel a squeeze were either not there or were well margined. This was not a squeeze.
Liquidations are across all assets we track. Bitcoin and ether are the bulk; on 23 September the largest single-asset figure was $4.4M of bitcoin longs, followed by $3.5M of Zcash longs — the privacy-coin trade taking its first real hit.
What this means
- The rally was bought in spot. Cheap funding, no short squeeze and long liquidations on up-days all point the same way. That is generally a healthier base than a leverage-led move, because the buyers do not have a margin call waiting.
- Leverage is present but not the driver. $26.6B of bitcoin OI is real money; the point is that it did not _grow_ out of proportion to price, and it is not paying up to stay long.
- Watch funding, not price, for the turn. If this rally becomes a leveraged one, the first sign will be annualised funding sustaining above 20% with OI rising faster than price. Neither is happening at the time of writing.
- Zcash is the leveraged trade of the moment. Fifth in OI and second in long liquidations on 23 September, it is where the froth is concentrated — not in bitcoin.
_Method note._ Funding rates and open interest are polled every five minutes from each venue's public API and stored as snapshots; the daily figures above are averages of the 00:00, 08:00 and 16:00 UTC settlements for Binance, Bybit and OKX. Liquidations are from the venues' public liquidation streams, aggregated by day and side, in USD notional at the time of the event. Bitunix reports funding but not open interest and is excluded from OI totals. Annualised funding is the eight-hour rate × 1,095.
Assets in this piece
 Bitcoin
 Ethereum
 Zcash
Sources
- Coinmico derivatives feed — funding, open interest and liquidations from Binance, Bybit, OKX, Bitget, Gate, Hyperliquid, Bitunix
- Coinmico BTC price index
Everything else in this piece is measured by Coinmico across the venues and chains we index. See our methodology.